Click on the image below to donwload the pdf file.
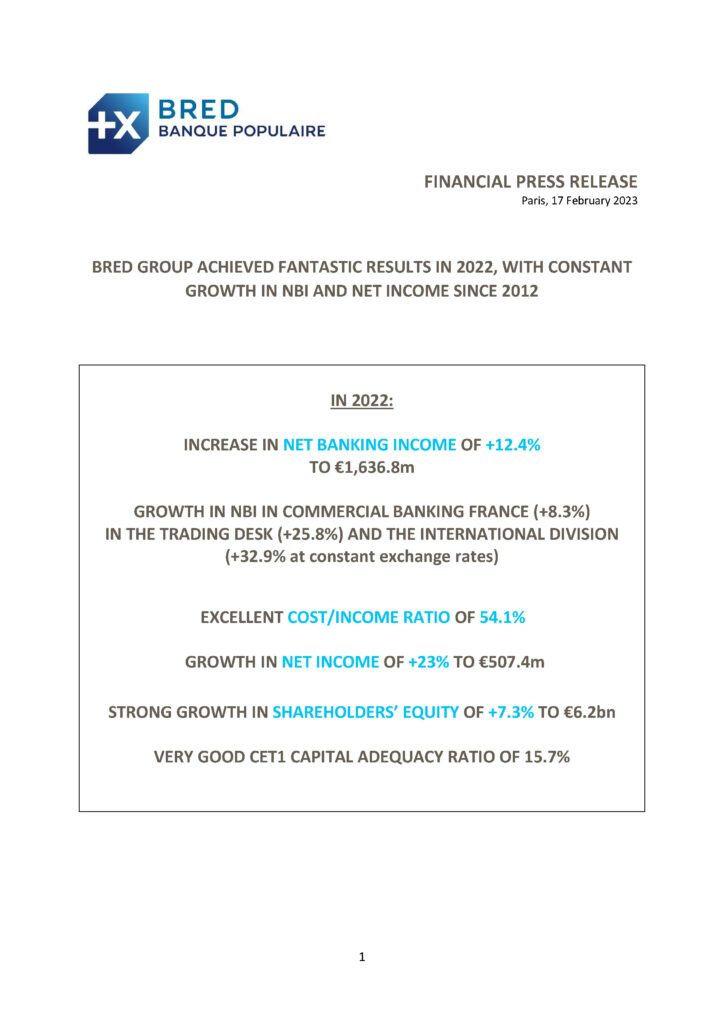
Click on the image below to donwload the pdf file.
In December 2022, the BRED Group’s Trading Room won three CMDportal awards on two key criteria: the total volume of deals and customer satisfaction.
🏆 Best European Money Market Dealer;
🏆 Best NEU CP Money Market Dealer;
🏆 Best Corporate Money Market Dealer.
These awards were won against renowned trading rooms. The BRED Group therefore wished to share this success in the print version of “Les Echos” and online, in English, on the “Bloomberg” website for its customers in Europe.
2022 will have been another successful year for the BRED Group despite economic, sanitary and geopolitical uncertainties. This remarkable momentum, which should be reflected again this year in our annual results, was illustrated by a number of successes:
BRED Banque Privée elected “Best Private Bank” in France in 2022 by the Sommet du Patrimoine et de la Performance.
BRED’s trading floor was awarded 3 CMDportal Money Markets Awards.
An A1 Sustainability Rating from Moody’s.
The opening of a branch in Dubai by our subsidiary BIC BRED Suisse.
New innovative products and services for our customers worldwide: retirement planning tool, split payments and services for professionals with “BRED Services Pro+” in France; payment by QR Code and in-store fast personal loan request in the French Overseas Departments; deployment of the 100% advisory branch concept in Djibouti and of the BRED Business Connect application for BRED Bank Fiji and BRED Bank Cambodia.
This is another year of collective successes that I would like to salute here.
I would like to thank the BRED Group’s employees for their commitment. Their expertise and involvement are the cornerstone of the no-distance banking model that I have been defending since 2012; a model based on high value-added advice and a local relationship that is part of the long term.
I would also like to thank all our individual, professional and corporate customers in France and abroad for their trust and loyalty. It is an honour to accompany you in your projects, which I hope will be numerous and full of success in 2023.
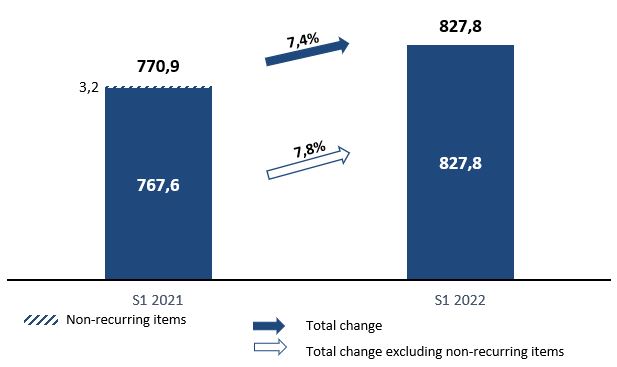
NET BANKING INCOME AT €827.8M UP +7.4%
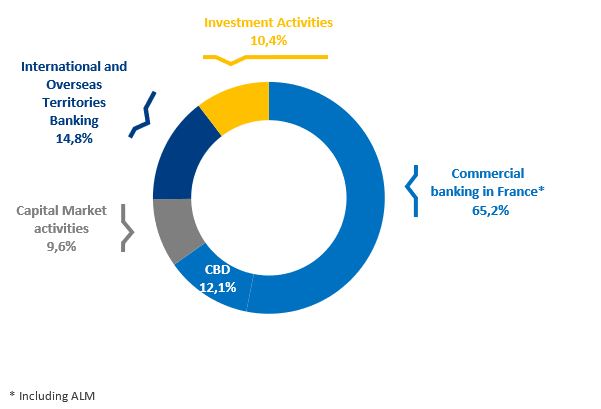
GROWTH IN NBI IN COMMERCIAL BANKING FRANCE (+8.6%) AND THE INTERNATIONAL DIVISION (+ 39.6 % at constant exchange rate)
EXCELLENT COST/INCOME RATIO AT 53.9%
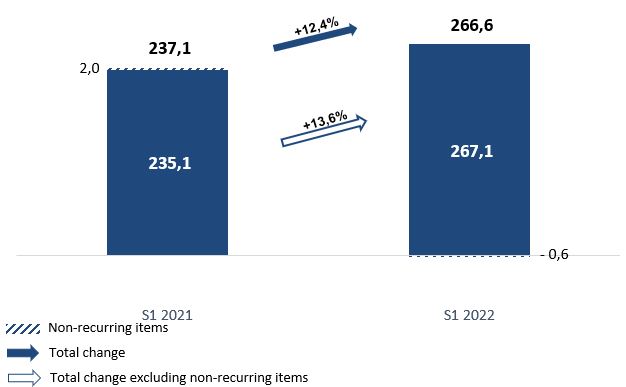
NET INCOME OF €266.6 M, UP +12,4%
SHAREHOLDERS’ EQUITY AT 5.8€bn
The BRED Group recorded consolidated half-year net banking income (NBI) up +7.4%, to €827.8 million. Excluding exceptional items, NBI increased by 7.8%. It benefits from the excellent momentum of the various divisions: commercial banking in France (mainland and overseas), Corporate Banking Division and from the continued development of international subsidiaries.
Operating expenses increased by 9%. Restated for the increase in variable compensation resulting from the improvement in results, operating expenses increased by 7.7%, reflecting IT investments and support for the growth of our subsidiaries.
As a result, the gross operating income increased by 5.5% (6.6% excluding exceptional items), to reach a remarkable level, at €381.7m at the end of the first half of 2022.
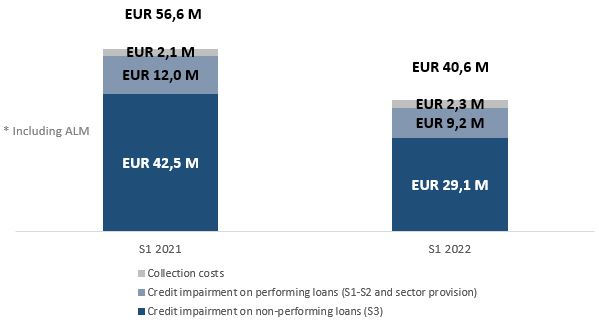
The cost of risk, under control, and with no effect of sectoral provisions reversal, was down 28% and represented €40.6 million.
The half-year Net Income (NI), Group share reached a level of €266.6 million, witnessing the solidity of the BRED Group. Excluding exceptional items, it amounted to €267.1 million.
Shareholders’ equity amounted to €5.8 billion as of June 30, 2022, with an overall solvency ratio of 15.3%.
The BRED Group achieved excellent results in 2021, with an NBI of €1,456m and net income of €412m, up respectively by 61% and 129% since 2012. The BRED Group’s cost-to- income ratio of 55.1% and the change in its shareholders’ equity emphasise the effectiveness and strength of our bank, and its ability to contribute, alongside its customers, to the development of its territories.
These achievements are driven by all of our businesses, and in particular by commercial banking in France, which recorded an increase in revenue in 2021 of 5.4% and a continuous cumulative increase of 50% since 2012, thereby easily outperforming the market. Abroad, the BRED Group has also strengthened its positioning with growth in NBI of 25.7% at constant exchange rates, despite the closure of borders due to the pandemic in some countries where we are present. Finally, our trading desk maintained a very good level of earnings.
2021 was also a year in which BRED achieved recognition. In particular, it was chosen by the European Commission to place its bond issues, won second prize in the category “best affiliated private bank” at the Sommet du Patrimoine et de la Performance, won an award for the best banking individual retirement savings plan on the market, and was awarded the Label of Excellence by the Dossiers de l’Épargne. Not forgetting that its subsidiary in Laos was named the best corporate bank in the country.
However, beyond the figures and awards in 2021, what I retain above all from that year, and what represents our main source of collective pride, is the relevance of the strategy introduced ten years ago: banking without distance, which has given rise in recent years to “100% advisory banking”. This strategy is an unprecedented source of resilience in an environment that is still heavily constrained by the structure of interest rates, the technological revolution, and more recently by the health crisis. It has guided all our decisions to combine the protection of employees with support for our customers and territories. Applied to each of our businesses, it has enabled us to achieve outstanding performance over the last ten years.
Behind this approach and at the basis of our culture of efficiency is a multidimensional philosophy of proximity and added value.
Local proximity to our customers first of all, which we have endeavoured to strengthen in recent years and to significantly improve. Indeed, banking without distance shows the BRED Group’s ability to meet the ever-increasing expectations of individuals, professionals and companies of all sizes, both in terms of the overall long-term relationship and of services and advice. It shows the relationship of trust that we are continually striving to enhance: trust in our ability to support our customers on a long-term basis in their personal or corporate projects. Trust as well in our ability to meet their needs for financing, sound investments and data protection.
This philosophy also covers our proximity to the territories. We are a cooperative bank, with a particularly strong role in the territories where we are established, both in France and abroad. We are in perfect harmony with them, with converging interests. If one day, one of our territories shows lower profitability than others, the savings collected there will be used to finance the development of projects in those territories, and will not be allocated to another territory offering better profitability.
The third aspect of proximity concerns decision-making; our customers know the people ultimately in charge at BRED and its banking subsidiaries, and decisions are made at the most local level.
Finally, managerial proximity, which is just as essential, because commercial banking is a business that involves consulting, and the ability to mobilise teams to support customers sets us apart. Our employees are involved in the strategy, we give them the keys not only to understand it but also to be key players in it.
The added value of advice to all our customers is one of the foundations of our strategy. Customers, who are better- informed and more exacting, expect to have advisers who can meet their specific needs, and who are highly competent. This is what the BRED Group strives to offer and which has resulted in the emergence of “100% advisory banking”.
Banking without distance means knowing that it is essential to be one of the best players in digital technology, but this is not enough. The future of the BRED Group is therefore also rooted in the philosophy of an overall close relationship that we mentioned earlier.
Based on this conviction, we have created a banking model that is as efficient in the field of transactions as online- only banks, but with a crucial extra element that makes it possible to completely satisfy customer requirements: high value-added personalised support. We have undertaken to enhance the overall close relationship that BRED maintains with its customers, in each of its territories, by focussing our thinking on human capital, which is irreplaceable. Far from closing our branches, we have reorganised them to dedicate them entirely to advisory banking. We have continued to train our employees in order to perfect their expertise in the customer segment they cover, thereby improving our quality of advice, responsiveness and proactiveness.
At the same time, we have invested heavily in new technologies to offer a better customer experience, in particular with a daily banking application recognised as one of the best on the market. Furthermore, we have used digital technology to free our advisers and support departments from low value-added tasks. Finally, we have developed non-banking services.
Although our banking without distance strategy has guided us for almost 10 years, the cooperative dimension represents our roots. Our members are customers, men and women from all sectors who contribute to the economic and social dynamics of the territories where we are present.
This model meets our customers’ expectations, as is shown by the success of BRED’s capital increases.
Thanks to this original status, BRED’s strategy does not depend on the financial markets, their volatility and herd behaviour, such as the very short-term pressure they impose.
Our cooperative model looks to the long term, and is inclusive and committed to the territories, and is therefore more relevant than ever, as in essence it tackles the major transitions currently under way, and makes the issue of social engagement central to our model, our strategy and our governance.
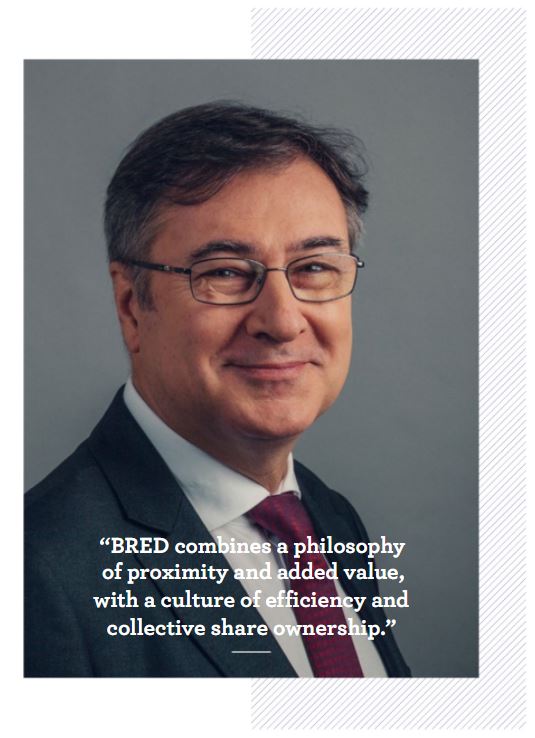
As a cooperative bank, without distance, BRED combines a philosophy of proximity and added value, with a culture of efficiency and collective share ownership.
To cope with the challenges of the future, it will continue to deploy this joint model of capitalism with a positive impact, in which the customers and members, as well as the employees and the company as a whole, are central to its strategy.
Practices, but also accounting rules, have their influence on the behaviour of banks and the non-banking sector, two complementary but competing segments. Regulation also has its role. Hence the need to think about regulation for non-banks.
The financial system, which matches the financing capacities of some with the needs of others, consists of banks and financial markets. These two components of the system have partly identical and partly separate roles. Both help finance economic players. Market finance has seen a sharp increase in its share worldwide since the great financial crisis. It now accounts for around 50% of financing in general, and 30% in the corporate sector. It is also useful that investment funds, asset managers and institutional investors, major players on the financial markets, take part in financing. Because banks alone cannot guarantee the full amount to be financed.
Markets accept risks denied by banks
In addition, they can provide capital to companies that find getting finance from banks more difficult, including start-ups and innovation in general. Explanations: the credit risk of these sectors is generally too high for banks, which must protect the deposits entrusted to them. Investment funds may accept that they may lose more, if on average capital gains on companies that will survive and succeed are greater than losses, with the final risk being taken by end investors who accept it.
The two types of player in the financial system are also different in terms of financial stability. Firstly, because banks record the historical value of the loans they grant on their balance sheets. They must provision for the risk on a statistical basis, but also on a case-by-case basis depending on their assessment of a possible deterioration in each borrower’s ability to repay. However, changes in average opinions on risk quality are not taken into account and do not result in any accounting changes.
A different approach to risk
The approach is completely different for funds: they must record the change in the market value of their financial investments at each point in time, in accordance with fair value accounting rules. This leads to a significant difference in behaviour between banks and funds. Banks choose to grant credit based on their analysis of the borrower’s ability to repay over time. For their part, funds choose to buy bonds, for example, based on what they think about changes in the market’s majority view on the value of the risk premium allocated to the borrower. Why lend if they think the value of the bond will fall in the near future, even if they are not ultimately worried about non‑repayment? Unless strongly conditioned by the prospect of securitisation of the loans granted or the resale of risks by CDS, banks’ behaviour is therefore much more stable by nature than that of funds, whose valuation mechanisms are much more volatile, since they are much more related to self-referential behaviour on the markets.
On the other hand, funds do not take on financial risks themselves. Credit, interest rate and liquidity risks are in fact left in the hands of end investors, households or companies. In the case of banking intermediation, banks bear these risks on their own income statements. And they do so in a professional, regulated and supervised manner. This allows households and businesses not to take these risks if they do not have the competence or the desire to do so.
Increased risk-taking from very low rates
Banks and non-bank financial intermediaries such as funds are therefore both very useful, both competitive and complementary. But the portion granted to each in the global financial system plays a major role in overall stability or instability. We should add a fundamental point, which the major central banks are currently addressing. Since the financial crisis of 2007-2009, the regulation of banks has increased significantly, notably through the required capital adequacy ratios (more equity for identical risks) and the setting of restrictive ratios limiting liquidity risk. There is no such regulation for non-bank financial intermediaries.
However, the monetary policy of very low interest rates for a very long time has gradually led financial players, on behalf of savers, to seek returns by increasingly taking on risk. In terms of credit risk -including increasingly high leverage effects- with squashed risk premiums. And in terms of liquidity risk, by further extending the maturities of credit securities and lowering the expected level of their liquidity. This has made fund assets significantly more vulnerable, as highlighted by all the studies of organisations responsible for supervising financial stability around the world. The risk can thus be pushed out of the banking system and onto non-bank financial agents, without control.
Beware of moral hazard!
The violent financial crisis of March 2020, triggered by the expected impact of the pandemic, was fortunately brought swiftly under control by the central banks. They acted very strongly and very quickly. In this regard, it demonstrated the resilience of banks, but also the vulnerability of many funds. Central banks had to buy very large amounts of securities from funds in difficulty, including high yield. They had to prevent a catastrophic chain of events, due in particular to sudden withdrawals from end investors that these funds could not absorb without incurring excessive losses or without a major liquidity crisis.
Prudential and macro-prudential regulation cannot do everything, but it is essential to mitigate the natural procyclicality of finance and to prevent the risk of financial instability as much as possible. It must now be extended and adapted to non-banking financial intermediaries. It is also essential to combat moral hazard, because without preventive regulation and with bail-outs during major crises, risk-taking may be ever higher, with no limit or almost, thanks to a free option given by central banks against serious incidents. Finally, the proportion between banks and non-banks in the financial system as a whole must also be subject to adequate analysis and policies to determine the most favourable balance for both growth and financial stability.